TradingKey - Amgen (AMGN) has multiple pipeline programs in October that should advance the programs, while newer products help replace the biosimilar and price competition erosion on older products. Amgen closed trading on October 7 at $413.08, up $10.48 or 2.60% on the day and down 7.6% from the August 25, 52 week high of $447.03.
What is interesting is how much more diversified the growth story has become. Repatha has continued to post strong cardiovascular growth, while the latest data for Imdelltra has expanded its role in small cell lung cancer, and Tezspire has posted positive Phase 3 data in eosinophilic esophagitis (EoE), and dazodalibep has also produced strong Phase 3 data in autoimmune disorders. MariTide is still the larger growth opportunity, but has more company now with the other pipeline products.
Dazodalibep Delivers a Fresh Phase 3 Pipeline Win
On September 22, Amgen announced positive topline results from the Phase 3 OASIZ 301 study of dazodalibep in patients with moderate-to-severe systemic Sjögren’s Syndrome. Amgen indicated the study met its primary endpoint with a statistically significant and clinically meaningful improvement in the systemic disease activity at the 48 week mark.
Amgen noted the effect was early and sustained. Improvement in ESSDAI disease activity score was observed starting at week 4 and sustained at week 48. Detailed results will be presented at a future medical meeting, and as such, topline results provide encouraging but preliminary data.
The strategic importance of the result is clear. Positive Phase 3 results provide the opportunity to establish a new commercial franchise outside of obesity, oncology and cardiovascular therapy. Another Phase 3 study, OASIZ 303, which is in patients with high symptom burden and low systemic activity, is ongoing and will complete in the fourth quarter of 2026.
Imdelltra’s Commercial Potential Keeps Expanding
Imdelltra is quickly becoming one of the larger components of Amgen's oncology business. During Q2 of 2026, it generated $288 million in revenue (up 115% versus Q2 2025). The higher revenue was the result of a greater volume of treatment. During Q3 2026, the data and regulatory updates strengthened the view on the addressable market and caused the potential market to expand.
On September 8, Amgen and Astra Zeneca announced positive results of the Phase 3 DeLLphi-305 study. The study evaluated the first-line maintenance treatment of Imdelltra in combination with Imfinzi, versus Imfinzi as a single agent, for the treatment of patients with extensive-stage small cell lung cancer (ES-SCLC). The study met its primary endpoint of overall survival. Key secondary endpoints of progression-free survival and objective response also were met.
On September 14, the Food and Drug Administration (FDA) approved an update to Imdelltra's prescribing information reducing recommended monitoring for the first two doses from 22 to 24 hours to 6 to 8 hours from the start of infusion. The patients still require a next day assessment, but the update should allow for more practical application in community oncology.
This operational change is important from a commercial perspective. A therapy can have great efficacy and still have issues with adoption if the burden of administration is too great. Lowering the burden of monitoring can help eliminate some of the barriers to broader usage while keeping the clinical profile the same.
Repatha Could Address a Much Larger Cardiovascular Population
As mentioned earlier, Repatha is another important growth catalyst. In the second quarter, Repatha posted sales of $953 million, up 37% from the prior year. That puts it at a $4 billion annual run rate. The more exciting news came on August 31st with the release of pre-specified analysis of the VESALIUS-CV trial.
The analysis looked at the effect of Repatha in 12,257 high-risk adults who did not suffer a prior heart attack or stroke and compared it to a placebo. Repatha reduced the risk of death by 20% when added to statins or other LDL-lowering therapies. The median length of follow up was 4.6 years.
The results should broaden the opportunity set, but I would be cautious of expectations. This was a prespecified analysis and not a new indication. The label, regulatory review and how the broader dataset is evaluated by physicians will be very important to go forward strategy.
Tezspire Adds Another Potential Indication
Positive results for the TEZSPIRE Phase 3 CROSSING study were announced August 27th by Amgen and AstraZeneca. TEZSPIRE was studied in patients ages 12-80 with eosinophilic esophagitis (EoE). The two co-primary endpoints were histologic remission and the frequency and severity of dysphagia (difficulty swallowing). Both endpoints were statistically and clinically significant at the 24 week (interim) time point. Benefits were sustained at 52 weeks.
The positive results in EoE are meaningful for TEZSPIRE as the drug is already a significant growth driver. Q2 sales for TEZSPIRE rose 42% to $486 million. Success in EoE would broaden the drug’s indications beyond respiratory conditions.
Multiple late stage assets in Amgen’s pipeline increase the potential for new indications across several therapeutic areas. The pipeline reduces the dependence for long term success on a single clinical study.
MariTide Remains the Biggest Long-Term Wild Card
MariTide is a differentiated antibody-peptide conjugate that activates the GLP-1 receptor and antagonizes the GIP receptor. The progress of its Phase 3 MARITIME program in 2026 will shape future regulatory and commercial expectations for MariTide.
The Phase 3 MARITIME program is currently evaluating MariTide in chronic weight management, type 2 diabetes, CVD outcomes, heart failure and obstructive sleep apnea. Additionally, studies are looking at patients switching from weekly tirzepatide or semaglutide to MariTide (quarterly or every-eight-week dosing).
MariTide’s dosing profile is the most unique feature. The goal of long-acting drug design is to facilitate monthly dosing. Clinical studies are currently testing 4-6 doses per year. A previous Phase 2 study of MariTide for obesity showed up to ~20% average body weight loss without type 2 diabetes.
There is no lack of competition. Other next-generation obesity therapies are being developed by Eli Lilly, Novo Nordisk, Roche, Pfizer and numerous other biotech companies. Ultimately, MariTide will have to differentiate based on more than percent body weight loss. Tolerability, CVD outcomes, and how well the effects are maintained with less-frequent dosing will likely be just as important as the headline body weight loss percentage.
Q2 Shows Strong Growth Despite Legacy Drug Pressure
Amgen's Q2 results show strong revenue growth of 10% from last year, reaching $10.1 billion. Product sales also grew by 9% to $9.2 billion. Non-GAAP EPS grew by 4% to $6.29 and free cash flow also increased to $3.5 billion.
Amgen updated their full year 2026 guidance, increasing revenue expectation to a range of $38.2 to $39.4 billion and non-GAAP EPS to $22.30 to $23.50. Their six key growth drivers accounted for approximately 70% of Q2 sales and increased by 26% from last year.
As expected, the mature portfolio continues to be a headwind for the business. Prolia, Xgeva, Otezla, and Enbrel are all still facing biosimilar/price/competitive pressures. Positive growth for other products, like Repatha and Evenity, Tepezza, Uplizna, Tezspire and Imdelltra, helps offset the declines for the mature products.
Debt Remains an Important Balance-Sheet Risk
At the end of Q2, Amgen had $14.0 billion in cash and cash equivalents and $57.3 billion of debt. Debt is one of the major constraints for financial flexibility, mainly due to the Horizon Therapeutics acquisition.
Operating cash flow for Q2 was $4.0 billion and free cash flow was $3.5 billion. Management expects approximately $2.6 billion of capital expenditures for the year. Amgen expects to maintain a positive cash flow position and cover dividend payments while also funding pipeline investments. The balance sheet is important since Amgen is supporting a broad, late stage development program. Should growth flatten or a major development program fail, the debt would impact Amgen's valuation.
The Next Earnings Date Is Not Yet Official
As of the 8th of October, Amgen had not released Q3 earnings date on their investor relations calendar. Outside market calendars estimate Amgen will release their earnings report around November 3. Until Amgen officially announces this, I would consider this estimate speculative.
For the next earnings report I will look at the growth of Repatha, the adoption of Imdeltra with the easing of some of the monitoring requirements, the progress of Tezspire, erosion of Amgen's legacy products, full year guidance, and any changes to the MariTide Phase 3 studies. I will also monitor if the newer growth franchises are progressing to help offset the biosimilar threat.
The market is already assigning value to Amgen's pipeline with the share price of $413.08. The biggest upside in my view would be the pipeline products delivering strong results and MariTide Phase 3 progressing well. The biggest threats are erosion of legacy products, competition in obesity, and a large debt load.
Amgen Technical Analysis: AMGN Holds Above $406 as $426 Becomes the Next Breakout Test
AMGN rebounded from the $396 to $406 zone and closed at $413.08 on October 7. Price is now trading above both of the short-term moving averages. This is a good sign, and, together with the defense of the rising trendline, gives a positive outlook for the continuation of the recent price recovery.
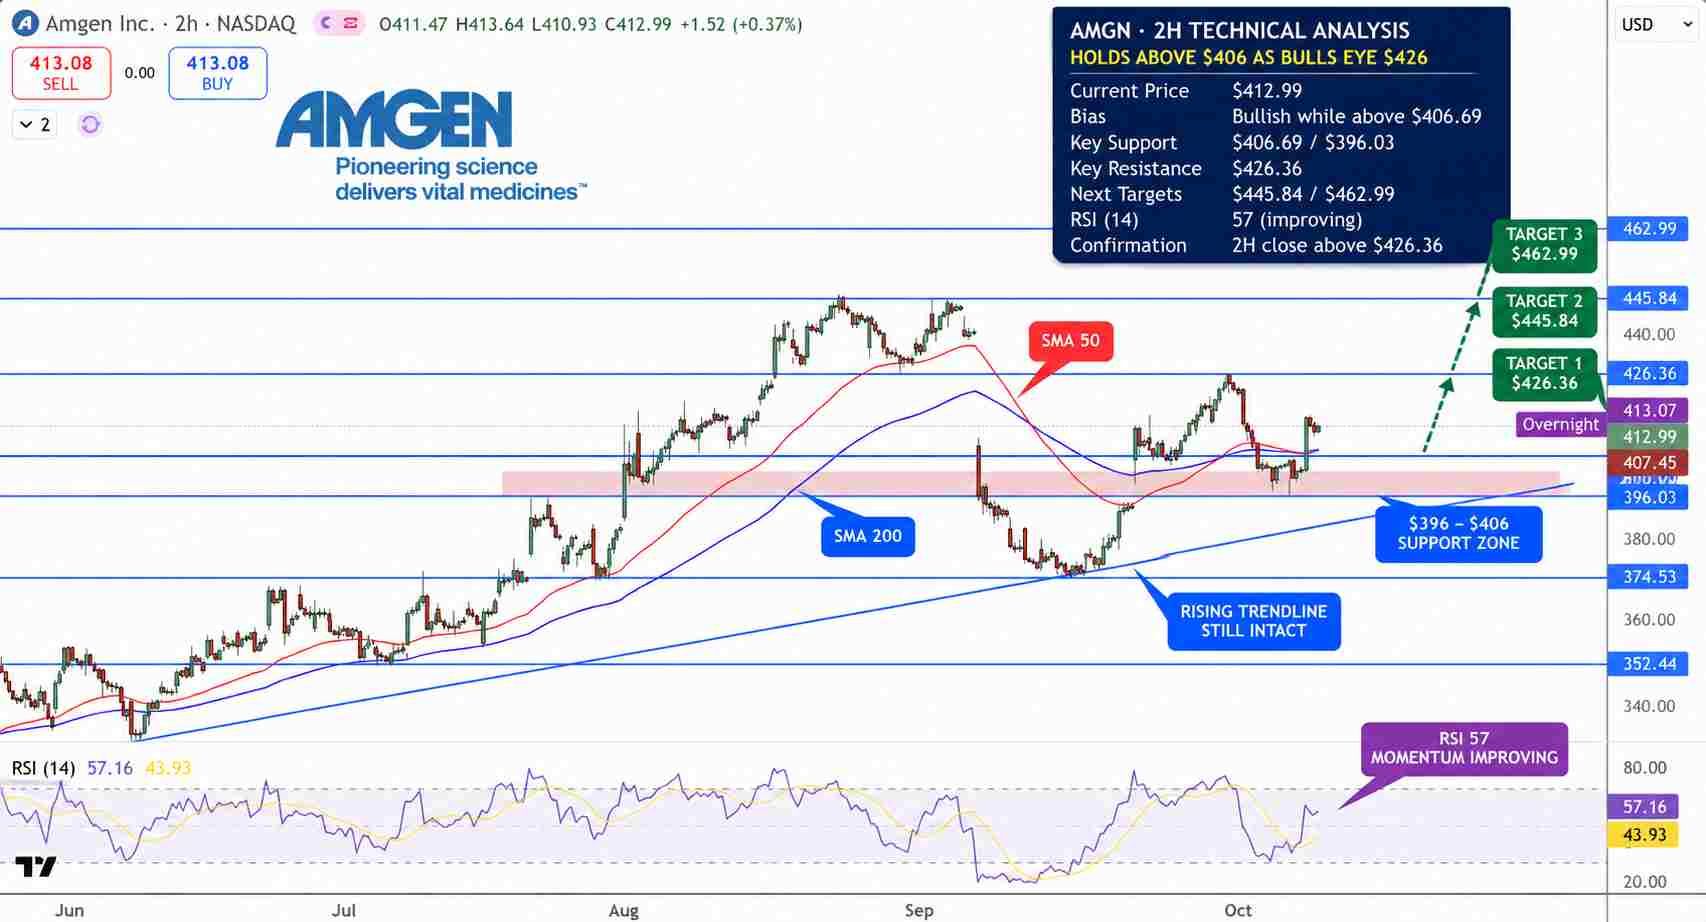
Amgen Stock Price Chart - Source: Tradingview
RSI also improved to the 57 area and is above its signal line at 44, suggesting that upward momentum is improving. The first important resistance is seen at $426.36.
A break above $426.36 would expose $445.84, and ultimately $462.99. On the downside, initial support is at $406.69, with the $396.03 level coming in below that.
While AMGN trades above $406.69 and the rising trendline, my bias will remain bullish. Confirmation would come with a clean break and close above the $426.36 level.
Key Levels
• Latest completed close: $413.08
• Major support levels: $406.69, $396.03, then $374.53
• Major resistance levels: $426.36, $445.84, then $462.99
• RSI: approximately 57, improving
• Breakout target: $445.84 above a confirmed $426.36 break
Why is Amgen stock in focus now?
Amgen has multiple late-stage programs advancing at the same time. Dazodalibep reported positive Phase 3 Sjögren’s results, Imdelltra got first-line survival data and easier monitoring, and Tezspire reported positive Phase 3 results in EoE. Repatha added stronger primary-prevention evidence, while Imdelltra added first-line maintenance survival data.
What level confirms a stronger AMGN breakout?
A move above $426.36 would confirm an intermediate-term breakout, and make a move toward $445.84 more likely. A drop below $396.03 would greatly reduce the likelihood of a longer-term bullish view.
Bottom Line
One year ago, the market was focused on negative news stemming from loss of patent exclusivity and competition for Amgen’s older drugs. Repatha, Imdelltra and Tezspire, along with other newer drugs, helped to offset the loss of sales from the older drugs. Dazodalibep and MariTide offer exciting opportunities in autoimmune and obesity drug development, respectively, and add to Amgen’s drug pipeline. While competition is intense for MariTide, Amgen’s overall drug pipeline is strong enough that the focus on one drug is not needed to support the overall investment thesis. Technically, Amgen remains bullish as long as it trades above $406.69, and a clear close above $426.36 increases the chance it will move to $445.84.
Find out more